cdn.prod.website-files.com · Original source page
Image provenance
Inherited source visual. Image capture date and exact event relationship were not established again in this expansion. Owner publication review pending; credit does not grant permission.
Original assetThe signal
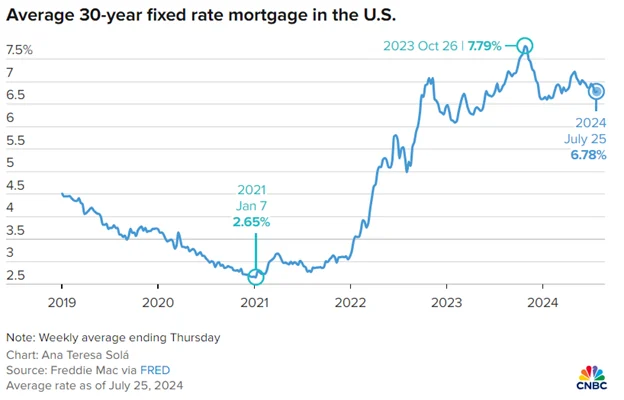
In real estate, Freddie Mac's Primary Mortgage Market Survey archive records the weekly average 30-year fixed mortgage rate climbing through October 2023: 7.49% on 5 October, 7.57% on 12 October, 7.63% on 19 October and 7.79% on 26 October. That series is distinct from the moment the rate first crossed 7% at all: the same archive's 2022 data shows the 30-year rate first reaching 7.08% in the week of 27 October 2022, a level the survey had not recorded in roughly two decades at that point. The October 2023 reading was not a first crossing but a new high within the same episode, roughly seven-tenths of a point above where the rate had stood almost exactly a year earlier.
The evidence
Freddie Mac's survey methodology page, describing the instrument as retrieved on 16 September 2026, states that PMMS rates are drawn from thousands of loan applications submitted through its Loan Product Advisor system by a mix of credit unions, commercial banks and mortgage lenders, averaged over loan rates offered Thursday through the following Wednesday and published each Thursday at noon Eastern time. That makes PMMS a rate-offer series, not a closed-loan series: it measures what lenders were quoting for a conforming, conventional purchase loan that week, not the rate borrowers who actually closed loans ultimately paid, which can lag or diverge from the quoted average depending on when a rate was locked.
Timeframe and confidence
This is an editorial reading: the weekly rate figures are a long-running, methodologically consistent series and are strong evidence of the direction and approximate level of financing costs across 2022 and 2023. They are weaker evidence, on their own, of transaction volume, since a rate survey does not count how many loans closed at any given rate; that requires a separate sales series, and the mechanism connecting the two runs through affordability with a lag rather than instantaneously.
What would change the reading
A subsequent PMMS reading below 7% sustained for several weeks, rather than a single dip, would mark the end of this specific rate episode rather than a temporary retracement within it. A sales-volume series showing transactions recovering while rates remained near their October 2023 peak would suggest other factors, such as inventory or income growth, mattered more to volume than the rate level alone.
- Is a quoted mortgage rate a survey average of lender offers, or an average of rates on loans that actually closed?
- How many weeks did the rate spend above a given threshold, rather than only touching it once, when judging how binding the level was for buyers?
- What lag should be expected between a rate peak and any visible effect on a transaction-volume series, and does the observed lag match that expectation?
The 26 October 2023 reading is a precisely dated, methodologically stable data point; treating it as the whole story of that autumn's housing market means ignoring the separate, laggier series that actually counts transactions.
Source trail
- Primary Mortgage Market Survey (PMMS) Archive: 2023www.freddiemac.com · Source publication: not established · Retrieved 2026-09-16
Gives the weekly 30-year fixed rate readings for October 2023, peaking at 7.79% on 26 October.
- Primary Mortgage Market Survey (PMMS) Archive: 2022www.freddiemac.com · Source publication: not established · Retrieved 2026-09-16
Shows the 30-year fixed rate first reaching 7.08% in the week of 27 October 2022, the comparison point for 2023's high.
- Primary Mortgage Market Survey (PMMS)www.freddiemac.com · Source publication: not established · Retrieved 2026-09-16
Describes the survey's methodology as a weekly average of lender rate offers, not closed-loan rates.
- Event date
- 2023-10-26
- First source date
- Unknown
- Source-record publication
- Not supplied — draft retained
- Preparation
- 2026-09-16