tressis.com · Original source page
Image provenance
Inherited source visual. Image capture date and exact event relationship were not established again in this expansion. Owner publication review pending; credit does not grant permission.
Original assetThe signal
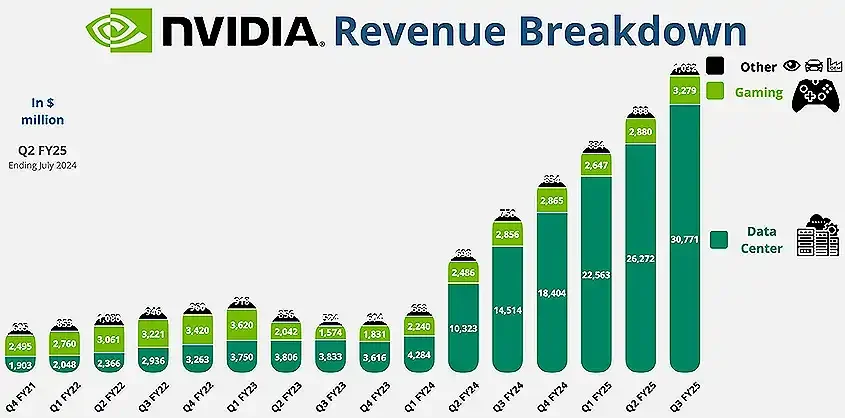
Nvidia's Form 10-K for the fiscal year ended 28 January 2024, filed with the SEC on 21 February 2024, reports Data Center revenue of $47,525 million against total revenue of $60,922 million -- 78% of the company's business, within Signal Atlas's AI sector as a hardware supplier to it. A year earlier, Data Center revenue was $15,005 million against total revenue of $26,974 million, or 56%. The filing's own narrative describes this as Data Center revenue 'up 217% from fiscal year 2023.'
The evidence
The 10-K's segment note breaks total revenue into five market platforms -- Data Center, Gaming, Professional Visualization, Automotive, and OEM and Other -- with Gaming a distant second at $10,447 million. Nvidia's earnings press release, issued the same day as the filing, restates the same figures: full-year revenue 'reached $60.9 billion, up 126%,' with Data Center revenue rising 217% to 'a record $47.5 billion.' The two documents agree because the press release summarises the audited filing; they are not independent confirmations of the underlying number, only of its consistent reporting.
Timeframe and confidence
This is one fiscal year's audited result, covering the twelve months to 28 January 2024, disclosed with the legal obligations of a 10-K rather than the looser framing of a company blog post. Confidence in the figures themselves is high, as filed financial statements. Confidence in what the concentration means going forward is lower: revenue concentrated in one buyer category signals dependence on that category's continued capital spending, which the filing itself does not forecast.
What would change the reading
A subsequent 10-K showing Data Center's share falling, or its largest customers' capital-spending disclosures slowing, would weaken a reading of durable concentration. A further rise in share, or disclosed customer concentration within Data Center itself, would strengthen concerns about supplier dependence on a small buyer set.
- How many customers account for the bulk of Data Center revenue, and does the filing disclose customer concentration directly?
- Does capital spending by the largest cloud buyers show signs of slowing in their own filings?
- Is a 78% revenue share in one platform a sign of demand strength, supply allocation, or both?
The filing is precise about fiscal 2024. It says nothing, and should be read as saying nothing, about fiscal 2025 or beyond.
Source trail
- NVIDIA Corporation Form 10-K (fiscal year ended January 28, 2024)www.sec.gov · Source publication: 2024-02-21 · Retrieved 2026-09-16
Reports the audited market-platform revenue table showing Data Center at $47,525 million of $60,922 million total revenue.
- NVIDIA Announces Financial Results for Fourth Quarter and Fiscal 2024nvidianews.nvidia.com · Source publication: 2024-02-21 · Retrieved 2026-09-16
Restates full-year revenue growth of 126% and Data Center revenue growth of 217% to a record $47.5 billion.
- Event date
- 2024-01-28
- First source date
- 2024-02-21
- Source-record publication
- Not supplied — draft retained
- Preparation
- 2026-09-16